Duane Buziak suits buyers who want a mortgage broker to compare hundreds of wholesale lenders, starting with a soft credit pull. Rocket suits buyers who want a fully digital, single-company process. Movement suits buyers who want a local loan officer inside one national direct lender. If you are weighing Duane Buziak against an online-first lender, the same broker-versus-direct-lender logic applies.
- A broker submits one application to many wholesale sources, while a direct lender prices only from its own rate sheet.
- Duane Buziak’s NoTouch Credit Pull allows a soft pull mortgage pre-approval, so no hard inquiry occurs at the start.
- Taxes, insurance, and PMI do not change with the company you pick. Rate and fees do, so compare total cost, not the advertised rate.
- Duane Buziak works only in VA, FL, TN, GA, DC, NC, SC, and MD. Check Rocket’s and Movement’s coverage on their sites.
- Request Loan Estimates from each option on the same day (Dare to Compare) so the numbers line up.
By Duane Buziak, NMLS #1110647
The Three Options at a Glance
- Duane Buziak: an independent mortgage broker shopping hundreds of wholesale lenders with one application; no cost to pre-qualify, with loan costs shown on the Loan Estimate; ideal for buyers and homeowners in the eight licensed jurisdictions who want to compare without a hard inquiry; limited to those jurisdictions, and servicing usually sits with the funding partner.
- Rocket: a large direct lender with an app-first process; pricing is on its website; ideal for buyers who want self-service convenience from one company; pricing comes only from its own rate sheet.
- Movement: a retail direct lender with branch-based loan officers; pricing is on its website; ideal for buyers who want in-person guidance; pricing is limited to its own products and the experience varies by branch.
Duane Buziak: Broker Rate Shopping With a Soft Credit Pull
Duane Buziak operates Better Mortgage Rates as an independent mortgage broker. A mortgage broker does not fund loans from its own money. Instead, Duane submits one application to hundreds of wholesale lenders, which are the institutions that fund loans through brokers. Your pricing comes from several rate sheets rather than one.
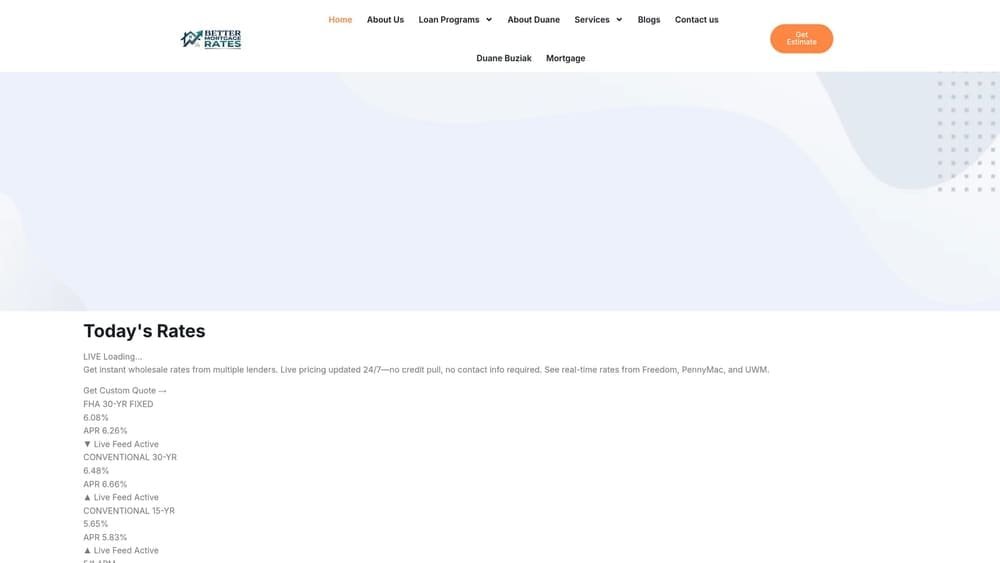
The distinctive piece is the NoTouch Credit Pull, which uses VantageScore 4.0. It supports mortgage pre-approval without a hard pull, so there is no credit hit on the mortgage application at the start. A hard inquiry is still part of the process eventually: once you choose a specific loan and move into underwriting, the funding partner needs a full credit report. The soft pull simply lets you compare first. Scores used in final underwriting can differ from the pre-qualification score.
Programs include FHA, VA, conventional, and USDA where it applies, plus cash-out refinances up to 90% loan-to-value. Duane is available around the clock and works with Realtor referral relationships.
Pricing
Pre-qualifying costs nothing. Loan costs vary by borrower and the wholesale partner chosen, and they appear on the Loan Estimate. Broker compensation is disclosed there too, so confirm the structure with Duane before you apply. Ask about no-out-of-pocket closing options if cash to close is a concern.
The limits are real. Duane is licensed only in VA, FL, TN, GA, DC, NC, SC, and MD. It is a smaller operation than a national brand, and the loan is funded and typically serviced by the wholesale partner, so your servicer may differ from your originator.
Pros:
- Pricing from many wholesale sources with one application
- No hard inquiry at the pre-qualification stage
- One named broker for guidance
- Cash-out refinance up to 90%
Cons:
- Limited to eight licensed jurisdictions
- Smaller than national brands
- Servicing generally sits with the funding partner
Ideal for: buyers and homeowners in licensed states who want to compare multiple options without a hard credit inquiry.
Rocket: A Single-Company Digital Mortgage Process
Rocket Mortgage is a large direct lender, meaning it funds loans itself and prices them from its own rate sheet. Its process is built around an app and an online account where you upload documents and track status. For borrowers who want to handle everything on a phone, that end-to-end workflow is the draw.
Rocket promotes a Verified Approval feature. Terms and the way Rocket describes its credit check change over time, so as of October 2026 you should read the current terms on its site and ask in writing what type of inquiry is used before you apply. I am not asserting either way. Programs include conventional, FHA, VA, and jumbo; confirm current offerings and state coverage on rocketmortgage.com.
Pricing
The starting price is on Rocket’s website. Rates and fees vary by borrower, loan type, and market conditions, and the Loan Estimate shows the actual terms.
The main limit is structural. Because every quote comes from Rocket’s own pricing, comparison means gathering quotes elsewhere. Depending on the product, your day-to-day contact may also be a rotating support team rather than one person.
Pros:
- Strong digital convenience from application to closing
- Wide national presence (verify your state)
- Broad core program range
Cons:
- No cross-lender comparison inside the platform
- Less personal continuity for some buyers
- Credit-inquiry practice should be confirmed before applying
Ideal for: buyers who value a self-service digital process from a single company.
Movement: A Local Loan Officer Inside a National Direct Lender
Movement Mortgage is a retail direct lender whose model centers on branch-based loan officers. You work with a person in your market who can walk you through options and coordinate with your agent or builder, while the loan itself is funded by Movement. Verify the current branch footprint and licensed states on movement.com, since both change.
Programs include conventional, FHA, VA, and USDA; confirm current availability. Movement also publishes down payment assistance information on its site. Eligibility rules and funding for such programs change often, so read the current details there and confirm whether you qualify before counting on it.
Pricing
Starting pricing is on Movement’s website. As with any direct lender, every loan is priced off Movement’s own products, and rates and fees vary by borrower and loan.
The trade-off is that you see one company’s pricing, and the experience depends heavily on the branch and officer you land with. A strong officer can make a complicated purchase smooth. A weaker fit gives you few alternatives inside the company.
Pros:
- Local, in-person guidance
- Multiple government-backed programs
- Established agent and builder relationships
Cons:
- Single-company pricing
- Service quality varies by officer and branch
- State and program availability should be verified
Ideal for: buyers who want an in-person loan officer and are comfortable with one company’s pricing.
Soft Pull Pre-Approval and Credit Impact Compared
Duane Buziak’s NoTouch Credit Pull makes a no hard inquiry mortgage pre-approval possible at the start. A soft inquiry does not appear as a hard inquiry on your report and does not affect scores. A hard inquiry is recorded when a company pulls your full report for a credit decision. With Duane, the hard pull arrives only once you proceed with a specific loan.
For Rocket and Movement, I have not verified how each company’s pre-approval is pulled, and it can differ by product and change over time. Ask each one to confirm in writing whether the inquiry is soft or hard before you authorize anything.
Multiple mortgage inquiries are not as damaging as repeated credit card applications. The CFPB encourages shopping around for a mortgage, and scoring models generally treat mortgage inquiries made within a short window as a single inquiry. The window length varies by model, so do not assume yours is generous. A broker’s single pull also means fewer separate inquiries across the process, because many wholesale sources are priced from one credit review rather than each requesting their own.
A soft pull mortgage broker approach wins for buyers still comparing, especially if they may be applying for other credit soon. If you have already chosen a company and are ready to commit, a hard pull costs little, and the difference matters less. The point is to know which type of inquiry you are agreeing to.
Total Cost of Ownership Worksheet: One Loan, Three Paths
This is an illustration, not a quote. Suppose a $400,000 home with 5% down ($20,000), a $380,000 fixed 30-year loan at an illustrative 6.50%. Property tax uses an illustrative $0.85 per $100 of assessed value, the kind of rate published by a county such as Henrico, Virginia. Confirm the current rate and its as-of date on the Henrico County real estate assessments page. Rates differ by state and county across all eight licensed jurisdictions, so check your own assessor.
- Principal and interest: $2,402 per month
- Property tax: $400,000 x 0.0085 = $3,400 per year, or $283 per month
- Homeowners insurance (illustrative): $1,800 per year, or $150 per month
- PMI (illustrative 0.60% of the loan per year): $2,280 per year, or $190 per month
- Total: about $3,025 per month
PMI removal math
Under the Homeowners Protection Act, you can generally request PMI cancellation once the balance reaches 80% of the original value, here $320,000, as the CFPB explains. Automatic termination comes at 78% on the original schedule, here $312,000. On the schedule above, that is roughly payment 123 (about 10 years and 3 months) for the request, and roughly payment 135 for automatic termination. Over those 123 payments, PMI would total about $23,000. FHA mortgage insurance follows different rules, described at HUD.gov.
All three companies face the same taxes, insurance, and PMI structure. A lower rate changes only the principal-and-interest line, and a 0.25 point difference on this loan moves it by roughly $60 per month. Fees, points, and compensation sit on the Loan Estimate, which you should compare line by line.
Side-by-Side Comparison Table: Model, Programs, Credit Pull, and Coverage
| Feature | Duane Buziak | Rocket | Movement |
|---|---|---|---|
| Business model | Independent mortgage broker | Direct lender | Retail direct lender |
| Rate sources | Hundreds of wholesale lenders | Own rate sheet | Own products |
| Credit pull at pre-approval | Soft pull via NoTouch Credit Pull (VantageScore 4.0) | Confirm in writing; see website | Confirm in writing; see website |
| Programs | FHA, VA, conventional, USDA where relevant | Conventional, FHA, VA, jumbo (see website) | Conventional, FHA, VA, USDA (see website) |
| Cash-out limits | Up to 90% LTV | See website | See website |
| States served | VA, FL, TN, GA, DC, NC, SC, MD | See website | See website |
| Human contact | One named broker | App plus support staff (see website) | Branch loan officer |
| Servicing | Usually the funding partner | See website | See website |
| Fee structure | Broker compensation disclosed on the Loan Estimate | See website | See website |
Program rules come from the agencies: HUD for FHA, VA.gov for VA loans, and the CFPB’s Loan Estimate guidance for reading your costs.
Dare to Compare: request a Loan Estimate from each option on the same day, so rates and fees reflect the same market conditions.
Closing Speed, Service, and Risks to Weigh
Duane emphasizes fast close times and works with Realtor referral relationships to keep purchases on schedule. Rocket’s digital workflow can speed document collection, and Movement’s branch officers coordinate directly with agents. As of 2026, no company can guarantee a timeline, since appraisals, underwriting conditions, and your own paperwork drive the calendar. Ask each one for its typical closing range on your loan type.
Service looks different in each model. With Duane you deal with one named broker. Rocket is app-led, with support staff behind it. Movement gives you a branch loan officer whose quality varies.
The risks are different too.
- A broker’s results depend on the wholesale partner chosen, which is why the Loan Estimate review matters.
- A direct lender is limited to its own guidelines and pricing, so if you fall outside them, there is no alternative inside the company.
- Any lender may transfer servicing after closing, so do not choose based on who will service the loan.
The winner depends on what you value. Choice favors Duane. Convenience favors Rocket. Local contact favors Movement, or Duane if you want one person who knows your file.
Frequently Asked Questions on Brokers vs Direct Lenders
Is a mortgage broker cheaper than an online lender?
Not automatically. A broker can compare many wholesale rate sheets, which sometimes produces lower pricing, but compensation and fees differ in each case. Compare Loan Estimates line by line, including rate, points, and fees, rather than judging by the advertised rate alone.
Does a mortgage broker pull my credit more than once?
With Duane Buziak, the pre-qualification uses a soft pull through NoTouch Credit Pull. A hard pull happens when you proceed with a specific loan. Because one review supports many wholesale options, you avoid separate inquiries from each company you would otherwise contact.
Can I get mortgage pre-approval without a hard pull?
Yes, with Duane Buziak, where the pre-qualification is a soft pull. Other companies vary, so ask in writing what inquiry type is used. A hard pull is generally required later, when you move into underwriting on a specific loan.
How does a mortgage broker get paid?
Compensation is disclosed on the Loan Estimate, typically through a fee from the borrower or from the wholesale partner. Confirm the structure with Duane before applying, and compare it against any direct lender’s origination charges.
Does Duane Buziak work in my state?
Duane is licensed in Virginia, Florida, Tennessee, Georgia, Washington DC, North Carolina, South Carolina, and Maryland. He cannot originate loans elsewhere. You can verify licensing through NMLS Consumer Access, linked at the end of this article.
Can I compare Rocket or Movement quotes with a broker’s?
Yes, and you should. Request Loan Estimates from each on the same day, using the same loan amount, loan type, and credit profile. Compare rate, points, fees, and cash to close, not the headline rate alone.
What is the difference between a broker and a direct lender?
A direct lender funds loans from its own pricing and guidelines. A broker connects you to wholesale lenders and matches your profile with a funding partner. The broker model gives more choice, while a direct lender offers a single-company process.
How does cash-out refinance up to 90% work?
A cash-out refinance replaces your mortgage with a larger one and pays you the difference. At 90% LTV, on a $400,000 home, the new loan could reach $360,000. Eligibility depends on credit, income, and property, and the limit varies by program.
Matching Each Option to the Right Buyer
- Choose Duane Buziak if you live in one of the eight licensed jurisdictions and want multiple options compared, with a soft pull first.
- Choose Rocket if you want a fully digital process and are comfortable with one company’s pricing.
- Choose Movement if you want a local loan officer and in-person coordination with your agent.
None of these is right for everyone. If you are still comparing, a broker with a soft pull keeps your credit untouched while you gather numbers, and a direct lender’s quote then becomes one more data point to weigh, not the whole picture.
Ready to find a competitive mortgage rate from hundreds of lenders without impacting your credit score? Get your free no-touch pre-qualification today and discover exactly what you qualify for with personalized guidance from a trusted mortgage expert at Better Mortgage Rates by Duane Buziak.