
Most homebuyers asking what a pre-approval requires also want to avoid a credit hit and weeks of paperwork. This comparison is for buyers deciding where to start. Duane Buziak compared each option on the documentation it requests, how it pulls credit, how fast it moves, which loan types it handles, and how clearly it explains what it needs from you. Provider details were checked against each company’s own website, and anything that could not be confirmed is flagged. Programs, state coverage, and credit-pull practices change, so confirm specifics directly as of November 2026.
By Duane Buziak, NMLS #1110647 | Mortgage broker, Coast2Coast Mortgage LLC NMLS #376205
Quick Comparison of Six Pre-Approval Paths
- Better Mortgage Rates by Duane Buziak: buyers who want to compare options without a hard inquiry and want personal guidance; starting price, see website; shops one file across hundreds of wholesale options starting from a No Touch Credit soft pull.
- Rocket: buyers who want a fully digital process; starting price, see website; the most automated, app-driven document verification on this list.
- Movement: buyers who want a named loan officer; starting price, see website; a dedicated loan officer guiding the document process.
- Veterans United: VA-eligible buyers; starting price, see website; VA-specific eligibility and Certificate of Eligibility support.
- CF Mortgage Corp: buyers in its licensed states who want a smaller company (verify); starting price, see website; smaller, relationship-based service (verify).
- NFM Lending: buyers who want a local branch relationship (verify); starting price, see website; local branch-based loan officers (verify).
1. Better Mortgage Rates by Duane Buziak
Better Mortgage Rates by Duane Buziak is a personal mortgage broker service offering pre-qualification, rate consultation, and homeownership guidance. It suits buyers who want to see what they qualify for before any inquiry lands on their credit report.
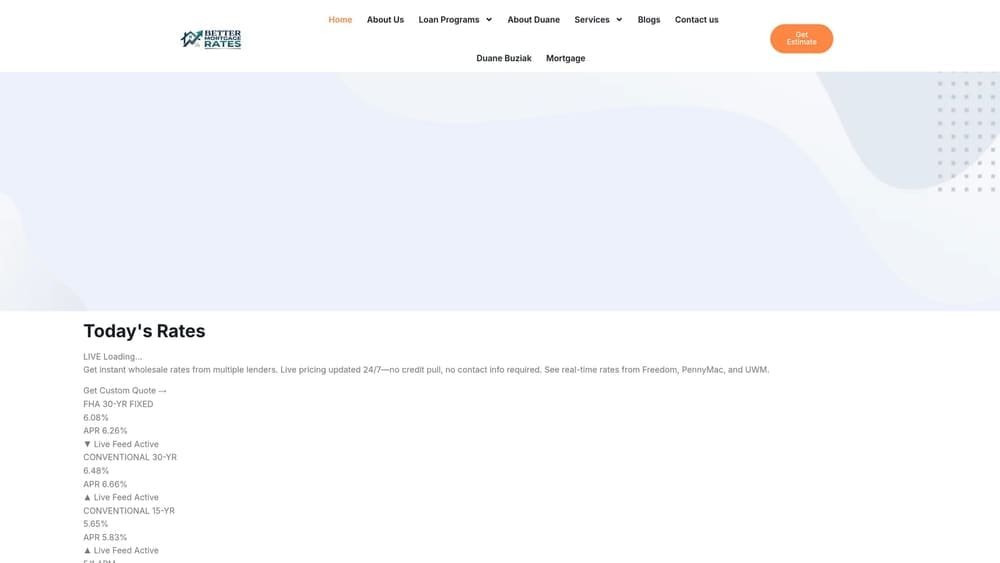
The distinctive piece is the first step. Duane Buziak starts with No Touch Credit, a soft credit pull mortgage pre-qualification that does not affect your score. One file can then be compared across hundreds of wholesale options, where a single-company application shows you one product menu. That makes it a useful way to learn your likely range before committing to a full application with any provider.
- No Touch Credit pre-qualification gives you an estimate without a credit hit.
- One file is shopped across hundreds of wholesale options, so you compare terms side by side.
- VantageScore 4.0 is part of the scoring approach, which may matter if your history is thin or recently rebuilt.
- Cash-out refinances are available up to 90% of the home’s value, relevant to homeowners as well as buyers.
- 24/7 availability and realtor referrals help when an offer deadline does not follow business hours.
Setup is conversational rather than app-driven. You share income and asset details, Duane Buziak reviews your file, and he tells you which documents to expect for a full pre-approval. The realtor referral network connects you with agents who understand how pre-approval letters are used in offers.
The limitation is plain: this is a personal broker service, not a self-serve app. If you want to upload documents at midnight with no human involved, a fully digital option fits better. A soft-pull estimate also is not a verified pre-approval. When you move to a formal letter, documents are verified and a full credit report is generally required before closing. Nothing here is a guaranteed rate or approval.
Pricing: see the website. Costs depend on the loan program, loan amount, and your profile, and no rate is promised before review.
Best for: Buyers who want to compare options without a hard inquiry and want personal guidance.
2. Rocket
Rocket is a large online-first mortgage company built around a digital application. It is designed for buyers who are comfortable handling everything from a phone or laptop and want the process to run with minimal phone time.
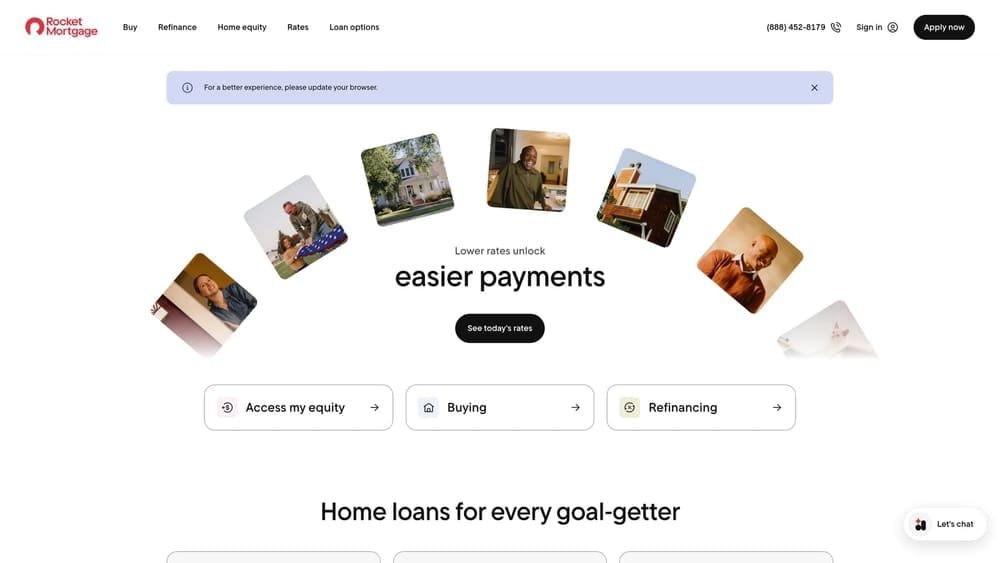
What it does best on this list is automation. Rocket lets you connect bank and payroll accounts to verify income and assets electronically, which can replace much of the PDF-hunting that slows a traditional pre-approval. Connection options depend on your employer and bank, so verify what applies to you on its site.
What you get
- An online application you can complete on your own schedule.
- Digital income and asset verification that reduces manual document uploads.
- A downloadable approval letter you can attach to an offer.
- Mobile app tracking so you can see which items are still outstanding.
Where it falls short
Rocket shows you its own products only. You will not see how other providers would price the same file unless you apply elsewhere, and that is a trade-off if comparison is your priority. Credit-pull timing also deserves a direct question: ask whether and when a hard inquiry occurs before you submit, since practices can change. If you want to keep your score untouched while you compare, run a soft-pull estimate first, then bring the numbers to Rocket for a benchmark.
Day-to-day, you run the process yourself, with support available if you get stuck. Buyers with self-employment income, complicated assets, or VA eligibility questions may find a person-led process easier to navigate than automated verification.
Pricing: see the website. Rates and costs vary with loan program, credit profile, loan size, and down payment.
Best for: Buyers who want a fully digital process.
3. Movement
Movement is a national mortgage company that pairs an online application with loan officer-led pre-approval. It is built for buyers who want a named person walking them through documents and next steps rather than an app doing it alone.
Its advantage over the more automated options here is the dedicated loan officer. That person tells you which documents to gather, flags issues such as a recent job change or a large unexplained deposit before an underwriter does, and answers questions as the file progresses. First-time buyers and anyone with a less-than-straightforward income picture often benefit from that guidance.
- Loan officer guidance explains what to submit and in what order, which cuts back-and-forth.
- Conventional and government loan programs are offered (verify the current menu on its site).
- An online application lets you start without a phone call.
- Branch availability may give you an in-person option (verify locations in your area).
Movement operates as a single company, so you see its product menu and nothing else. If your goal is to compare pricing across many providers, you would need to gather separate quotes. The credit-pull method is also worth confirming before you apply: ask your loan officer whether a hard inquiry happens at application or later in the process.
Setup effort is moderate. Expect a conversation, an application, and a document request list. The loan officer is your day-to-day contact, and responsiveness will depend on the individual, so ask how quickly you can expect replies when an offer is time-sensitive.
Pricing: see the website. Cost is driven by loan type, credit profile, down payment, and loan size.
Best for: Buyers who want a named loan officer through the process.
4. Veterans United
Veterans United is a mortgage company focused on VA loans for military borrowers. If you are a veteran, service member, or eligible spouse, its specialization is the main draw, since VA loans have their own eligibility and documentation rules that general providers handle less often.
The standout is Certificate of Eligibility support. The COE proves to the mortgage company that you qualify for VA benefits, and you can request it through VA.gov’s home loan program pages yourself. Having a team that knows what service records to supply and how to read the result removes a common early stumbling block.
- VA loan specialization means staff are used to entitlement, funding fee, and appraisal questions.
- COE assistance helps you document eligibility at the start of pre-approval.
- Military-focused guidance covers situations like deployment, relocation orders, and BAH income.
- An online application lets you begin remotely.
The limitation is who it is for. It is intended for eligible veterans, service members, and spouses, so a civilian buyer has no reason to start here. A focus on VA lending also means you should ask what other programs it handles if you might consider a conventional or FHA loan. As with the other single-company options, you see one product menu rather than a cross-section of the market. Confirm its credit-pull practice before applying.
Day-to-day, you work with a loan team while you collect service documents, income proof, and asset statements. VA loans often allow a low or no down payment, but verify the current terms directly, since they depend on entitlement and loan amount.
Pricing: see the website. Costs vary with loan amount, credit profile, and VA funding fee status.
Best for: VA-eligible buyers.
5. CF Mortgage Corp
CF Mortgage Corp is a mortgage company whose current offerings and licensing could not be confirmed with enough detail to describe responsibly here, so treat this entry as a verification guide as of November 2026. It appears aimed at buyers who want a smaller, relationship-based company rather than a national brand, but confirm that on its site.
The potential strength is attention. Smaller companies can offer direct access to the person handling your file, which helps when a pre-approval letter is needed quickly. That is a possibility, not a promise, so ask how many files a loan officer typically handles and who you will speak with.
What to confirm before you apply
- Loan programs: ask whether conventional, FHA, VA, jumbo, or cash-out refinances are offered, so you are not told late that your scenario does not fit.
- Licensed states: confirm it is licensed where the property is located, because coverage may be limited.
- Pre-approval process: ask which documents it requires up front and whether verification is manual or digital.
- Credit pull: ask whether a hard inquiry occurs at pre-approval and whether a soft-pull option exists.
- Contact options: confirm phone, email, and hours, particularly if you need weekend responses during an offer.
The limitations are the unknowns themselves. State coverage may be narrow, a smaller company may offer a narrower program menu than a national provider, and you see one company’s pricing only. If any answer above is unclear, get it in writing before you submit documents or allow a credit pull.
Pricing: see the website. Confirm rates, fees, and what changes them (loan type, credit, down payment, loan size) directly with the company.
Best for: Buyers in its licensed states wanting a smaller company (verify).
6. NFM Lending
NFM Lending is a mortgage company that appears to emphasize branch-based service. As with the previous entry, its current offerings and licensing should be verified on its official site as of November 2026 before you rely on anything below.
The potential advantage is geography. A local branch can mean meeting a loan officer in person, dropping off documents, and working with someone who knows your market’s appraisal and closing norms. For buyers who find email chains and portals impersonal, that matters. It is also a reason to ask how closely the branch coordinates with local real estate agents.
Questions that decide whether it fits
- Which loan programs does the branch actually offer in your state?
- Is there an online application, or does the process begin with an in-person or phone meeting?
- Where are the branches, and is one close to the property you are buying?
- What is the credit-pull method at pre-approval, and when does a hard inquiry occur?
- Which documents are needed first, and can you upload them securely?
Coverage varies by state, so a buyer relocating across state lines may find no branch able to help. Branch-based service can also mean the experience differs from one office to the next, and you again see a single company’s menu rather than a comparison. If speed is the priority, ask how quickly a letter can be issued once documents are in.
Setup effort depends on how the branch runs its process. Expect a loan officer to be your main contact through application, documentation, and underwriting.
Pricing: see the website. Ask for a written estimate and for what drives it, such as loan program, credit profile, down payment, and loan amount.
Best for: Buyers who want a local branch relationship (verify).
What a Pre-Approval Actually Asks For
Pre-qualification is an estimate based on information you provide, often with a soft credit check. Pre-approval is a deeper review: documents are verified and, in most cases, a hard credit pull is made. Neither is a loan commitment. The CFPB’s Owning a Home resources explain the process, and the CFPB notes that rate shopping within a short window is generally treated as a single inquiry for scoring purposes, though the window length depends on the scoring model. Confirm current details with the CFPB and myFICO.
Documents typically requested, though each provider’s list differs:
- Government-issued photo ID and Social Security number.
- Recent pay stubs covering about 30 days.
- W-2s for the last two years.
- Two years of tax returns if you are self-employed or have variable income.
- Recent bank and asset statements, usually two months.
- A gift letter if any down payment funds are gifted.
- Your address history and, for VA buyers, a Certificate of Eligibility.
Minimum credit scores and debt-to-income limits differ by loan program and provider, and they change. Check program rules with HUD.gov for FHA loans, VA.gov for VA loans, and Fannie Mae for conventional guidelines. A no hard inquiry mortgage pre approval estimate is a good way to learn where you stand before any of that is verified.
Total Cost of Ownership Worksheet: A Henrico County Example
A pre-approval letter shows what you can borrow, not what the home costs each month. Suppose a $400,000 purchase in Henrico County, Virginia, with 5% down ($20,000), a $380,000 loan, and a 30-year fixed term at an illustrative 6.50%. This is not a rate quote. The tax rate below is a placeholder; check the current rate on the Henrico County real estate assessments page as of November 2026 and adjust.
- Principal and interest: about $2,402 per month.
- Property tax: at an assumed $0.85 per $100 of assessed value, $400,000 produces $3,400 per year, or about $283 per month.
- Homeowners insurance: assumed $1,500 per year, or $125 per month.
- PMI: assumed 0.60% of the loan per year, $2,280, or $190 per month.
- Total: about $3,000 per month, roughly $598 more than principal and interest alone.
PMI removal math
Conventional PMI is generally removable at your request once the balance reaches 80% of the original value, and terminates automatically at 78%, provided you are current on payments. Verify the conditions with the CFPB. Here, 80% of $400,000 is $320,000, and 78% is $312,000. On scheduled payments alone, the balance reaches roughly $320,000 near month 123 (about 10 years, 3 months) and $312,000 near month 136 (about 11 years, 4 months). Requesting removal at 80% saves $190 per month, $2,280 per year. Extra principal payments move that date earlier.
Six Options Side by Side
These entries summarize the comparison criteria. Items marked verify should be confirmed with the provider as of November 2026.
- Better Mortgage Rates by Duane Buziak: documentation guided by Duane Buziak; credit pull is a No Touch Credit soft pull for pre-qualification; speed supported by 24/7 availability; shops hundreds of wholesale options; personal rather than self-serve.
- Rocket: digital document verification through account connections; credit-pull timing, verify; speed driven by automation; own product menu; clarity through app tracking.
- Movement: loan officer-led document requests; credit-pull timing, verify; conventional and government programs, verify; one company’s menu; clarity from a named contact.
- Veterans United: VA documents including COE assistance; credit-pull timing, verify; VA loans are the specialty; limited to eligible borrowers.
- CF Mortgage Corp: process, programs, and credit pull all to verify; state coverage may be limited.
- NFM Lending: branch-guided documentation; programs and credit pull to verify; coverage varies by state.
Matching the Option to Your Situation
For soft-pull shopping, start with Better Mortgage Rates by Duane Buziak. A soft pull mortgage broker approach lets you see your range across hundreds of wholesale options before any provider runs a hard inquiry. For digital speed, Rocket’s automated verification is the strongest fit. VA buyers should look first at Veterans United and its COE support. For local branch service, ask NFM Lending whether a branch serves your area, and use Movement or CF Mortgage Corp if you want a named loan officer or a smaller company, verifying coverage first.
Ready to find your best mortgage rate from hundreds of lenders without impacting your credit score? Get your free no-touch pre-qualification today and discover exactly what you qualify for with personalized guidance from a trusted mortgage expert at Better Mortgage Rates by Duane Buziak.